Micron's customers are putting money behind their demand forecasts. On September 30, the memory maker disclosed $32 billion in financial commitments across 26 Strategic Customer Agreements, or SCAs. I see that as the more consequential business development in its latest earnings report: buyers are accepting obligations that help their supplier plan years ahead, even though the chips they want still depend on factories being built and operated successfully.
The quarterly sales numbers were striking enough. Micron reported $54.23 billion in revenue for the fiscal fourth quarter ended September 3, compared with $41.46 billion in the previous quarter and $11.32 billion a year earlier. But one exceptional quarter cannot settle how much confidence a manufacturer should place in demand for the rest of the decade.
Before the results, Melissa Otto of S&P Global Market Intelligence's Visible Alpha identified the right area to examine: the durability of demand, and how Micron would handle pricing and longer-term contracts. Her September 22 analysis provides the starting question here. The new disclosures offer a partial answer. Customers are helping make expansion financially credible, while Micron retains the obligation to deliver. That is a useful change in who carries the risk, with limits worth understanding before calling the memory cycle permanently different.
Moving Beyond Demand Forecasts
A demand forecast tells a manufacturer what a customer hopes to buy. A purchase commitment gives both sides something firmer to plan around. The distinction becomes especially valuable when production investment must precede delivery by years: a supplier needs confidence that buyers will still want the output after the equipment has been installed.
Micron had already described this approach in its June earnings materials. At that point it had signed 16 strategic agreements, generally running through 2030, with shorter terms for automotive customers. The company described take-or-pay volume commitments and pricing arrangements that included floors and ceilings. The September report expands that existing approach; it does not mark the invention of long-term supply contracting.
The cash also needs careful interpretation. Of the new $32 billion commitment total, most represents deposits, but it is not all money already received. Micron reported a $12.7 billion deposit balance at the end of the fourth quarter. It says those funds are unrestricted and returnable in the latter half of the agreements when customers meet minimum purchase requirements.
That makes the deposits useful financing, with an associated obligation. They give Micron cash it can use while the commercial relationship runs its course. They also give the buyer a reason to take its promised purchases seriously. Neither side has simply handed the other a free option to change its plans without consequences.
Micron's annual cash-flow statement reinforces the distinction: it classifies proceeds from customer contract liability deposits under financing activities. Calling that money chip revenue would confuse a customer's support for the relationship with payment earned by supplying products. It would also make the operating business look stronger for the wrong reason. The business case for the agreements is already meaningful without counting the same customer relationship as several different financial wins.
The Price of Supply Assurance
Customers are making a trade. Committing funds and purchases can improve supply visibility, but it reduces their freedom to wait for a better deal. For an infrastructure buyer, the question is whether that loss of flexibility is worth reducing uncertainty around a component its plans require.
Micron's June explanation of its largest agreements shows how pricing can make that trade more acceptable. Existing products generally had ceilings around calendar second-quarter market prices, alongside floors; premiums for new products remained subject to negotiation. A ceiling can limit the buyer's exposure to a shortage-driven price increase. A floor can limit the supplier's exposure to a decline. Neither term promises that both parties will always receive the price they would have preferred in an unconstrained market.
September's update says roughly three-quarters of estimated SCA revenue has defined pricing, mostly using bands. The company estimates SCAs will represent over 35% of revenue through 2030. That is a revenue estimate, not a measurement of the share of factory capacity reserved. It also leaves substantial business outside this particular set of agreements.
The same care applies to Micron's roughly $150 billion of remaining performance obligations disclosed on September 30. This measure uses committed volumes and minimum prices in eligible contracts. It is neither cash in hand nor another amount to add to the $32 billion of financial commitments. One number describes future obligations to supply products; the other describes customers' financial backing for the agreements.
For judging the business, I would give more weight to how these arrangements perform than to the size of the aggregate number. A large contract book can support planning, but it cannot tell us by itself which products will earn the best margins, how demand will evolve, or how smoothly each customer will take delivery. The public totals help establish the scale of the commitment. They do not expose the complete commercial terms of every relationship.
Capital Still Has to Become Capacity
The manufacturing schedule explains why a customer might accept those constraints. Micron expects first wafer output from Idaho's ID1 facility in mid-2027, ID2 in late 2028 and its first New York fab in 2030. These are projected production starts, not promises that full capacity will be available on those dates.
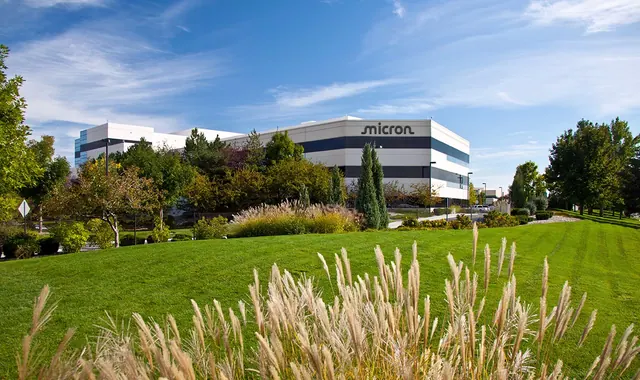
The existing Idaho expansion illustrates the distance between a visible construction milestone and saleable chips. Micron's project page describes the spring 2026 cleanroom blowdown, which prepares the controlled environment for manufacturing equipment. It is progress toward production, but a prepared building still needs equipment, qualified processes and an operating ramp. A photograph of a site cannot establish that those later steps are complete.
Reuters' September 30 reporting adds useful context from its interview with Micron chief operating officer Manish Bhatia: new production takes time to become meaningful supply. That distinction matters to customers planning their own infrastructure. The date of first output can be a milestone on their supplier's schedule without being the date on which they can equip an entire new deployment.
Here is where my reading of the agreements becomes more cautious. Customer financing improves Micron's ability to support expansion, but a stronger balance sheet cannot compress every stage of factory execution. A commercial agreement can allocate the consequences of delay. It cannot, on its own, qualify a manufacturing process or make a construction crew finish earlier.
Nor do the deposits prove that particular customers paid for particular fabs. The disclosed funds are unrestricted. It is reasonable to view them as support for Micron's overall ability to invest, but mapping each dollar to a named building would claim more than the company has disclosed. The connection is between customer commitment and corporate planning, rather than a publicly itemized customer-funded construction program.
For buyers, this creates two separate planning questions. How much supply have they secured commercially? And when can the supplier actually deliver it? Treating the first answer as if it settles the second would erase the very manufacturing uncertainty that makes long-term agreements attractive in the first place.
The Obligations Run Both Ways
Micron's regulatory disclosures provide the strongest check on an overly optimistic reading. Its June Form 10-Q warns that failures to deliver under strategic agreements can expose it to damages, while commitments can constrain supply allocation and commercial flexibility. It also describes the possibility of customers failing to honor obligations, with enforcement leading to disputes or damaged relationships. These are disclosed risks, not reports that the new agreements have already failed.
The important point is that securing a customer also creates a responsibility to that customer. If a supplier has promised volumes under agreed pricing terms, it cannot analyze every future sale as though that promise did not exist. A favorable market may make some contract terms less attractive than an uncommitted transaction would have been. That is part of the price of obtaining earlier certainty.
Buyers face their own dependencies. The same filing identifies energy, water and capital constraints affecting customers' data-center expansion. A customer could remain committed to AI investment while encountering delays elsewhere in its project. In that situation, wanting memory over the long term and needing a scheduled delivery immediately are different things.
This is why a forecast of continuing AI demand is insufficient to evaluate the contracts. Demand can remain strong in aggregate while timing, product mix or individual customer circumstances change. A contractual obligation makes those changes more consequential to the parties; it does not prevent them from occurring.
There is also no basis for treating every agreement as a pure high-bandwidth-memory deal or assigning particular contracts to famous AI companies whose names were not disclosed. Micron serves a wider memory and storage market. The sensible conclusion is narrower: its customers have accepted substantial commitments in exchange for supply assurance, and Micron has accepted substantial commitments in return.
What Would Make the Change Durable
The next useful evidence will be operational. Do customers take the volumes they committed to? Does Micron deliver them on the agreed terms? Do new facilities move from initial output to meaningful production as planned? Those questions connect the financial promise to the physical product without requiring a prediction about the exact date of the next downturn.
Pricing will matter too. A contract that both sides value during a shortage may feel different if supply becomes easier to obtain. That does not mean a dispute or renegotiation is inevitable. It means the benefit of greater certainty must be judged over the life of the agreement, including conditions less favorable to one party than those prevailing when it signed.
My judgment is that Micron has strengthened the commercial foundation for expansion. Customers' willingness to commit purchases and financing is more useful than enthusiasm expressed in a forecast. But the manufacturer still has to make and deliver the chips, and the customer still has to find productive uses for them. The agreements make that shared dependence explicit. Their lasting value will be measured by fulfilled purchases and reliable supply, rather than by treating every committed dollar as profit already earned.