The Sovereign Price Tag
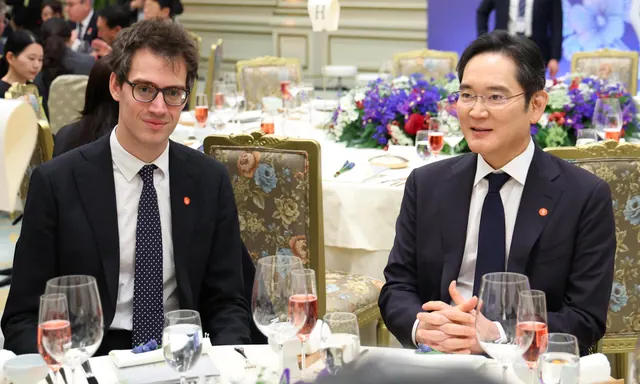
When Mistral announced its €3 billion Series D financing round, lifting its post-money valuation past €21 billion, the company framed the transaction as a decisive victory for European technological autonomy. Led by South Korea’s Samsung Electronics alongside Scaleup Europe Fund (managed by EQT) and existing backer PSG Equity, Mistral hailed the transaction as the largest equity financing round ever achieved by a European technology enterprise. Just one year earlier, in September 2025, the company had closed a financing round that valued it at €11.7 billion, according to reporting by Alexandre Piquard in *Le Monde*.
The capital injection is massive by any European standard, yet it arrives precisely when the company faces mounting scrutiny over its core identity. In its official announcement, Mistral declared that the proceeds would expand frontier research, secure training compute, scale international operations, and broaden its infrastructure. At the same time, Samsung described an accompanying strategic partnership aimed at semiconductor infrastructure, taking an equity stake that binds the Paris-based AI firm closely to an overseas hardware giant.
For AI practitioners and technology buyers, the question raised by this financing is straightforward: What exactly does €3 billion purchase in the pursuit of "sovereign" AI?
The short answer is that €3 billion buys time, hardware allocations, and enterprise runway. It does not buy independence from global supply chains, or settle whether Mistral is chiefly a frontier lab or a regional cloud and integration provider. I do not see the move down the stack as a capitulation. It may be the only credible way to pay for frontier research in Europe. But it changes the promise against which Mistral should be judged.
The Shift From Frontier Lab to Systems Operator
Mistral’s early reputation was founded on raw algorithmic efficiency. It emerged as Europe’s counterweight to American frontier laboratories, releasing high-performing open-weight models that punched far above their computational weight classes. Over the past year, however, the center of gravity inside the company has visibly drifted.
As documented by *Le Monde*, industry critics increasingly argue that Mistral has diverted its focus from driving the absolute model frontier toward operating physical data centers, hosting third-party models, and deploying engineers to build bespoke enterprise solutions. Rather than operating purely as a research-led foundation model provider, the company is assembling the operational apparatus of an enterprise services and hosting business.
This shift has created an internal and external tension that Alexandre Piquard captured when analyzing the round: Is Mistral still a pure frontier laboratory, or is it becoming a European cloud-and-services operator?
Mistral’s leadership rejects the premise that these two paths are mutually exclusive. Audrey Herblin-Stoop, Mistral’s vice president, told *Le Monde* that the company has by no means abandoned frontier research. Instead, she argued that vertical integration—selling hosting, managed services, and deployment architecture directly to organizations—is the very engine required to self-fund capital-intensive basic research. Herblin-Stoop also stated that Mistral expects to generate €1 billion in revenue for 2026, supported by an organization of roughly 1,200 employees, of whom about 300 are dedicated researchers.
| Metric or Dimension | Previous Milestone (Sept 2025) | Current Financing (Sept 2026) | Source / Context |
|---|---|---|---|
| Post-Money Valuation | €11.7 billion | > €21 billion | *Le Monde* / Company release |
| New Equity Capital Raised | Undisclosed in brief | €3 billion (Series D) | Official announcement |
| Lead Equity Investors | Previous investor consortium | Samsung Electronics, Scaleup Europe (EQT), PSG Equity | Official announcement |
| Disclosed Workforce | Not specified | ~1,200 staff (~300 researchers) | Company leadership via *Le Monde* |
| Disclosed Financial Target | Not specified | €1 billion revenue expected in 2026 | Company leadership via *Le Monde* |
| Ecosystem Footprint | Open-weight foundation | >125 enterprise clients across 20 countries | First-party company claims |
Herblin-Stoop’s figures need care. A €1 billion revenue expectation is not realized cash flow, and 300 researchers sit inside a 1,200-person company. Still, the logic is clear: Mistral is trying to turn enterprise integration into the revenue that pays for expensive research.
Relative Signals on the Open Board
While Mistral works to establish its commercial distribution engine, independent comparative indicators show that the gap between pure research specialists and practical systems integrators has real consequences on the public board.
In snapshot evaluations cited by *Le Monde*, Mistral Medium 3.5 held the 22nd position on the Artificial Analysis leaderboard. Concurrently, on the Hugging Face hub, models within the Mistral lineage had generated approximately 14,000 derivative versions since January. By comparison, Alibaba’s open-weight Qwen model ecosystem had accumulated roughly 151,000 derivatives over the same period.
| Indicator | Mistral Ecosystem | Qwen Ecosystem | Context and Nuance |
|---|---|---|---|
| Artificial Analysis Rank | Mistral Medium 3.5 ranked 22nd | Higher-tier comparative placement | Point-in-time public leaderboard ranking |
| Derivative Models (Hugging Face) | ~14,000 derivatives (since Jan 2026) | ~151,000 derivatives (since Jan 2026) | Platform fine-tuning activity metric |
These numbers do not prove that Mistral has lost the ability to produce frontier-grade intelligence. Benchmarks fluctuate, and derivative counts reflect hobbyist experimentation as much as enterprise adoption. They do show that Mistral is no longer an automatic first choice for open-weight experimentation.
Faced with massive open-weight releases from well-capitalized foreign incumbents and aggressive open-source initiatives from Asia, Mistral cannot rely solely on the intrinsic performance of its weights to capture market share. That dynamic accelerates its drive to differentiate through infrastructure delivery, private cloud operations, and contractual guarantees rather than relying purely on benchmark supremacy.
Dissecting the Sovereignty Stack
The commercial cornerstone of Mistral’s current pitch is the concept of "sovereignty." Yet in enterprise technology procurement, sovereignty is an ambiguous label. If the concept merely denotes the geographical location of a vendor's corporate headquarters, it amounts to little more than nationalistic marketing.
True operational sovereignty exists only when an enterprise can audit, control, isolate, or replace a mission-critical technology dependency. When Mistral’s stack is evaluated against these pragmatic criteria, the €3 billion raise highlights distinct areas of local autonomy alongside deep, inescapable foreign dependencies.
In its published white paper, Mistral establishes its own corporate definition of sovereignty, structuring it across four operational pillars:
- Strict physical and operational data localization.
- Direct customer control and deep customization of model weights.
- Private, dedicated, or fully predictable compute environments.
- Auditable, production-grade deployment architectures.
This is a cohesive framework for compliance-minded European enterprise buyers, but it is Mistral's self-selected framing rather than an established technical standard. Breaking the system down layer by layer reveals where the boundaries of that sovereignty actually lie:
The Hardware and Accelerator Foundation
At the physical foundation, genuine European autonomy remains largely illusory. Training and serving frontier-scale models requires state-of-the-art silicon, high-bandwidth memory, and advanced packaging technologies that European firms do not manufacture at scale. The strategic partnership accompanying this financing underscores that reality: the round was led by Samsung Electronics, an overseas conglomerate deeply rooted in memory and semiconductor manufacturing. Mistral can construct and operate data centers within European borders, but the accelerators, memory modules, and underlying fabrication tools running inside those facilities remain bound to international supply chains.
The Cloud and Operating Infrastructure Layer
At the infrastructure layer, Mistral’s expansion provides meaningful, demonstrable benefits to risk-averse buyers. By operating local infrastructure and providing fully private, on-premises, or isolated deployments, Mistral offers European organizations an alternative to the commercial cloud platforms governed by foreign regulatory jurisdictions. Mistral reports that it now supports more than 125 global enterprises across 20 countries, citing institutional clients such as Airbus, ASML, and HSBC. For enterprises bound by stringent confidentiality or banking directives, having a commercial partner deploy auditable weights inside local administrative perimeters provides practical isolation, even if the underlying compute hardware originated abroad.
The Weight and Governance Layer
At the governance level, Mistral asserts that control of capital and decision-making remains local. According to Herblin-Stoop, the founders and employees continue to hold more than half of the company's voting rights, and the equity base remains predominantly European despite significant foreign participation from Samsung. For customers, the critical sovereign variable is weight access: open-weight artifacts can be preserved, frozen, fine-tuned, and audited independently of the vendor’s continued existence or commercial policy changes. To the extent that Mistral continues releasing inspectable open weights, it provides users with structural switching power that closed API vendors fundamentally withhold.
The Realities Facing Enterprise Buyers
For corporate technology leaders and infrastructure architects, Mistral’s expanded capital base alters procurement economics.
The primary danger for buyers is conflating Mistral’s corporate European domicile with operational self-sufficiency. If an organization integrates a proprietary managed API hosted by Mistral’s cloud services, that organization has not achieved technological sovereignty; it has simply swapped an American or Asian managed services vendor for a French one. The customer remains completely exposed to provider lock-in, proprietary model deprecation, and unexpected pricing shifts.
True sovereignty emerges only when buyers leverage the inspectability and portability that Mistral's architecture allows. When a company deploys Mistral’s open weights within its own sovereign hardware enclosures, retains full custody of its fine-tuning data, and ensures its serving software can be transitioned to an alternative open-weight architecture without re-engineering the application layer, genuine independence is achieved.
Mistral’s pivot toward hands-on services and hosting makes it a far more capable enterprise partner today than it was as an unbundled research outfit. For large institutions like Airbus or HSBC, hiring a vendor that provides both state-of-the-art weights and the forward-deployed engineering muscle to implement them locally solves acute enterprise talent shortages. But buyers must see the transaction clearly: they are hiring an infrastructure and systems integrator that possesses an in-house model research arm, not merely purchasing an unbundled algorithmic breakthrough.
Two Tests for the Series D
The €3 billion Series D gives Mistral room to buy compute, retain researchers, and put engineers beside large customers. It does not settle what kind of company emerges from that expansion.
Yet the financing does not permanently resolve the fundamental contradiction identified by industry observers in *Le Monde*. As Mistral builds out data center capacity, implements bespoke enterprise projects, and relies on South Korean semiconductor partnerships, its identity will inevitably drift further away from that of a nimble, unencumbered research laboratory.
Whether this transformation represents a strategic compromise or a pragmatic masterstroke depends on two verifiable future signals:
First, practitioners must watch the composition of Mistral’s future model releases. If the company continues to train and release competitive, inspectable open weights that challenge top-tier frontier performance, its argument that vertical integration funds pure research will be validated. If its open releases slip further down public evaluation leaderboards or become secondary to proprietary API wrappers, Mistral will have effectively completed its transition into an infrastructure utility and services provider.
Second, the market must monitor Mistral’s revenue composition. If it reaches its €1 billion expectation through portable software, standardized serving, and infrastructure use, that supports the full-stack thesis. If the money comes chiefly from bespoke engineering hours, the result may still be a good business. It will simply be a different answer to the question Mistral started with. Sovereignty will not be proved by the nationality of the cap table; it will be proved when a customer can inspect a dependency, control it, and replace it without asking permission.